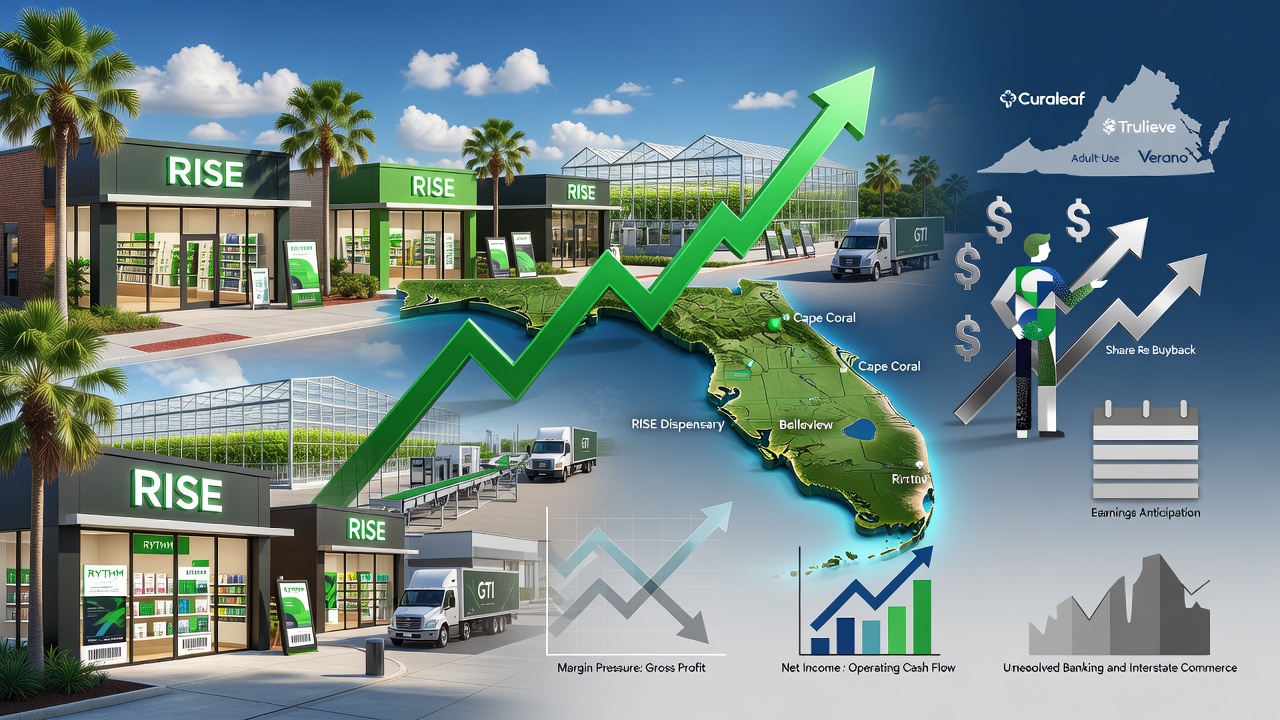
Green Thumb Industries (CN:GTII) shares rose 6.08% on October 21, 2026, a move that caught the eye of investors tracking the multi-state cannabis sector. The gain came amid new RISE Dispensary openings in Cape Coral and Belleview, Florida, alongside an active share repurchase program and anticipation of the company's next quarterly earnings release. No single catalyst has been confirmed as the direct trigger, but the backdrop is constructive.
What's Actually Driving the Story
Here's the catch with single-day stock pops in cannabis equities: they rarely trace back to one clean cause. Green Thumb's move coincided with store openings, not earnings, not a regulatory ruling. The Florida expansion adds two retail locations to an already sizable RISE network, and in a state with a large registered medical cannabis population, incremental storefronts matter for foot traffic and SKU turnover. But the timing also lines up with investor positioning ahead of quarterly results, and with a renewed buyback authorization that signals management confidence in cash flow. Put those together and you get sentiment, not proof of causation.
Vertical Integration as the Operating Model
Green Thumb runs cultivation, manufacturing, wholesale distribution and retail under one roof, a structure common among the larger multi-state operators. That vertical integration gives the company more control over product batches, lab testing timelines, and compliant packaging requirements across state lines - each with its own METRC tracking rules and labeling standards. The RYTHM brand licensing arrangement extends that model into branded product placement on dispensary menus beyond Green Thumb's own stores. In practice, though, vertical integration cuts both ways: it reduces reliance on third-party wholesale pricing swings, but it also means the company absorbs more of the capital burden when cultivation costs or input prices move against it.
The Margin Pressure Nobody Escapes
Green Thumb's latest reported quarter showed revenue growth, positive net income, and operating cash generation - genuinely solid numbers for the sector. Gross margins, though, remained under pressure. That's not unique to Green Thumb. Wholesale cannabis pricing has been compressing across most mature state markets as cultivation capacity outpaces demand growth, and 280E tax treatment continues to limit the deductions available to plant-touching businesses regardless of state-level profitability. Federal rescheduling discussions could eventually ease that tax burden for qualifying operators, but broader federal restrictions on banking and interstate commerce remain unresolved, so the compliance overhead doesn't disappear.
Competitive Position and What to Watch
Green Thumb sits alongside Curaleaf, Trulieve and Verano as one of the established multi-state operators with real retail scale. That scale helps with distribution reach and brand recognition, but it doesn't insulate against market saturation or price competition for retail customers. Key factors worth monitoring going forward:
- Execution discipline on new store openings - site selection and inventory management determine whether expansion pays off or drags on margins
- Virginia's evolving adult-use framework as a potential new market entry point
- Share repurchase activity as an indicator of management's confidence in free cash flow
- Upcoming earnings for signals on margin stabilization and gross profit trends
For operators, suppliers, and landlords watching the multi-state space, Green Thumb's trajectory is a useful proxy for how the broader regulated cannabis retail sector is absorbing regulatory uncertainty, competitive pricing pressure, and the slow grind toward federal policy clarity. None of that is resolved by a single strong trading session.